Mitihoon – SCG H1/2026 Adjusted Cash EBITDA Up 35% on Proactive Strategies; Cost and Feedstock Management, Strict Financial Discipline, Business Restructuring, Regional Optimization and HVA Products Drive Stronger Performance; Board Approves 3.5-Baht Interim Dividend to Support Shareholders; SCG Expects Continued H2 Volatility but Remains Confident in Resilient, Sustainable Growth
SCG announced stronger operating results for H1/2026, with Adjusted Cash EBITDA reaching 42,913 MB, an increase of 35% from the same period last year. This is the result of the successful implementation of proactive strategies that enhance agility through the “immediate action,” which includes managing costs through clean energy, timely sourcing of raw materials from non-Hormuz, and maintaining strict financial discipline, and the “medium-term action,” which focuses on business restructuring, driving High Value-Added Products (HVA), and adopting robotics and AI to enhance the efficiency of SCG’s manufacturing base across ASEAN. These efforts have led to improved operating results across all business units. SCG’s Board of Directors approved an interim dividend of 3.5 Baht per share, reflecting the company’s continued commitment to delivering value to shareholders. SCG expects the global economic environment to remain highly challenging in the H2/2026 but remains confident in its ability to navigate the situation with resilience. Looking ahead to next year, the ethane feedstock enhancement project at the Long Son Petrochemicals (LSP) complex in Vietnam is scheduled for completion. SCG will also continue to pursue collaboration with new business partners and is confident that these efforts will support sustainable growth.
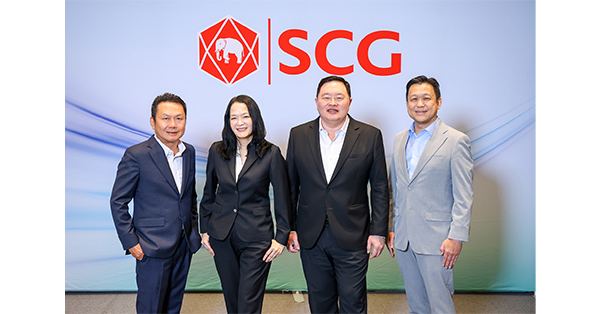
Thammasak Sethaudom, President and CEO of SCG, said, “SCG continues to build strength, agility, and competitiveness amid global volatility. As a result, the Adjusted Cash EBITDA (cash flow excluding inventory adjustment, impairment, and non-recurring items of business which are non-cash) for the H1/2026 increased by 35% from the same period last year to 42,913 MB. The successful execution of both our ‘immediate action’ and ‘medium-term action’ strategies has driven improved operating results across all business units. Cement, Building Materials, and Decorative Materials Business efficiently managed costs and addressed customer needs across ASEAN, while actively seeking growth opportunities with new business partners. Packaging Business showed improved performance, particularly in Indonesia, where the business returned to profitability. This turnaround was driven by stronger business integration following the merger & partnership of a fiber packaging manufacturing facility, enhanced operational efficiency, effective cost management, and increased domestic packaging sales volumes. Demand across ASEAN also continued to expand, particularly in Vietnam, which demonstrated strong growth. Chemicals Business focused on cost management, sourcing feedstock from non-Hormuz, and increasing sales of HVA products, enabling it to adapt promptly to volatility arising from the situation in the Middle East. The business was also supported by higher petrochemical spreads in global markets. Furthermore, SCG continues to maintain strong dividend income. Looking ahead to next year, several business transformation initiatives will be completed, including the ethane feedstock enhancement project at the LSP complex in Vietnam, while collaboration with new business partners is expected to become clearer. We are confident that these initiatives will drive SCG toward sustainable growth.”
For H1/2026, SCG reported total revenue from sales of 259,570 MB and profit for the period of 17,758 MB. Excluding extra items, which mainly related to inventory adjustments, profit for the period would be 12,649 MB.
In Q2/2026, SCG reported an Adjusted Cash EBITDA of 27,984 MB, total revenue from sales of 136,243 MB, and profit for the period of 11,535 MB. Excluding extra items, profit for the period would be 10,833 MB. Net debt decreased by 39,176 MB from the previous quarter. The net debt-to-EBITDA ratio improved to 3.7 times from 5.0 times in the previous quarter, and cash on hand at the end of Q2/2026 increased to 76,775 MB.
Key operational highlights for H1/2026 were as follows:
1.) Cement, Building Materials, and Decorative Materials Businesses were supported by government infrastructure projects in Thailand, as well as market growth in Vietnam and Indonesia, while the private sector in Thailand experienced a slowdown.
- SCG Cement-Building Materials reported a profit for the period of 5,790 MB and Adjusted Cash EBITDA of 11,407 MB, primarily driven by business restructuring and effective cost management.
Key operational highlights for H1/2026 were as follows:
- SCG has integrated SCG Cement and Green Solutions, SCG Smart Living, and SCG Distribution and Retail under the unified name “SCG Cement-Building Materials” as part of its One CBM approach. The integration, driven by a customer-centric operating model, aims to expand sales opportunities and improve efficiency across the business value chain. It enabled the businesses to leverage its ready-mixed concrete customer base to offer Non-RMC Products, resulting in a 15% year-on-year increase in cross-category sales, while expanding its sub-dealer network by more than 200 stores. The move also reduced operational redundancies and optimized shared resources, with expected cost and expense savings of over 1,000 MB within this year
- Accelerating the expansion of Smart Value Products (SVP), including Q-MAXX cement, through localized marketing strategies implemented in collaboration with distributors and partner construction-material retailers.
- Expanding the HVA product portfolio, including SCG DECAAR surface cladding and decorative materials for walls, ceilings, and floors in both interior and exterior applications. The product range offers diverse designs and material options, including fiber cement, aluminum, WPC, and vinyl.
- Continuing to drive the expansion of “SCG Low Carbon Cement”, which has already achieved market coverage of more than 80% in Thailand, while accelerating production and exports from Vietnam to serve growing markets that increasingly prioritize sustainability.
- Continuing to expand into Australian market, which has high potential by showcasing innovative products for residential and construction applications, including roofing, ceiling and wall systems, and thermal insulation, at “Sydney Build Expo 2026,” highlighting products that deliver quality, international standards, and sustainability.
- SCG Decor recorded Adjusted Cash EBITDA of 1,378 MB. The results were supported by growth in international revenue, particularly in Vietnam, together with effective management of financial resources, energy costs, and inventory although the Company had extra expenses of business restructuring and asset write-offs.
Key operational highlights for H1/2026 were as follows:
- Project progress on-track to expand glazed porcelain tile production capacity at PRIME in Vietnam to meet growing domestic and export demand. Upon completion of the project in 2027, PRIME’s glazed porcelain capacity will account for 40% of total production capacity.
- Commencing ceramic tile plant consolidation, alongside the installation of a new glazed porcelain tile production line equipped with an automation system in Thailand. The project is scheduled for completion in the Q3/2027 and is expected to reduce production costs per unit by up to 20%.
- Partnering with one of China’s leading sanitary ware component manufacturers to enter into the smart toilet market by establishing a manufacturing facility in Thailand with an annual production capacity of 96,000 units.
2.) Chemicals Business. The situation in the Middle East affected feedstock shortage and supply chains disruption. Consequently, several petrochemical plants suspended operations or reduced their operating rates, causing global supply to tighten. As a result, prices of polyethylene (PE) and polypropylene (PP) increased.
SCGC reported a profit for the period of 5,898 MB and Adjusted Cash EBITDA of 15,600 MB. This was primarily driven by higher petrochemical spreads, the company’s proactive management in accelerating raw material sourcing from non-Hormuz, enhancing plant operational efficiency (Optimization), increasing sales volumes of High Value-Added Products (HVA), and inventory adjustments.
Key operational highlights for H1/2026 were as follows:
- Divesting a 14.86% stake in PT Chandra Asri Pacific Tbk. (CAP) in Indonesia with the total proceeds of approximately 24,900 MB, which will be utilized towards deleveraging effort and the construction of the Long Son Petrochemicals (LSP) Ethane project in Vietnam.
- Accelerating preparations for the ethane feedstock enhancement project at the LSP complex in Vietnam, which is currently undergoing a temporary shutdown. Construction of the ethane storage tank has progressed by more than 60%, with operations scheduled to commence by the end of 2027 as planned.
- Continuing to accelerate the feasibility study for a strategic joint venture between GC and SCGC covering their olefins and polyolefins businesses in Thailand. Further progress will be announced Q3/2026.
3.) Packaging Business. Packaging demand recovered in Q2/2026, while raw material, energy, and freight costs surged due to disruptions from the Middle East conflict. SCGP has focused on enhancing operational efficiency to manage costs, ensure business continuity for customers, and strengthen competitiveness through its regional production network and integrated consumer packaging solutions.
SCGP reported a profit for the period of 3,870 MB and Adjusted Cash EBITDA of 10,472 MB, primarily driven by the return to profitability of its operations in Indonesia. This improvement was supported by higher domestic packaging sales volumes, selling price adjustment following regional market conditions, cost optimization, energy mix arrangement, and enhanced production efficiency, all of which enabled SCGP to achieve cost optimization targets. Meanwhile, the business in Vietnam continued to benefit from sustained economic growth and expanding domestic consumption.
Key operational highlights for H1/2026 were as follows:
- Expanding the paper packaging business across ASEAN to capture opportunities arising from continued demand growth. SCGP increased corrugated containers production capacity in the south of Vietnam.
- Driving business growth alongside sustainability by creating shared value with customers through the development of innovative products, services, and solutions that address both business requirements and ESG objectives. For example, SCGP collaborated with Kao Industrial (Thailand) Co., Ltd. (KAO) to develop packaging using mono-material innovation. This solution enables multilayer flexible packaging to be manufactured from a single type of material, making it more environmentally friendly and facilitating recycling.
- Applying AI, Machine Learning, and Deep Learning to enhance production efficiency, cost management, quality control, and data analytics, as well as deploying Collaborative Robots (Cobots) to improve the efficiency of repetitive tasks that require continuous operation.
Thammasak concluded, “Although the global economic situation in H2/ 2026 remains highly challenging due to uncertainty surrounding geopolitical conflicts, particularly the conflict in the Middle East, which shows signs of escalating, intense price competition, inflation, and volatile energy costs, SCG is confident in its ability to navigate these challenges with resilience with the strategies already implemented, which the company will continue to advance. SCG expects its full-year Adjusted Cash EBITDA to improve from 2025, enabling us to continuously deliver value to all shareholders and stakeholders.
“Looking ahead to next year, SCG will continue to accelerate its business transformation through its medium-term strategies. These include advancing the ethane feedstock enhancement project at the LSP complex in Vietnam, collaborating with new business partners, optimizing its manufacturing footprint across ASEAN, restructuring its management and operations, and adopting robotics and AI to enhance operational efficiency. With these initiatives scheduled for completion by the end of 2027, we are confident they will drive SCG toward sustainable growth.”
In addition, the Board of Directors has approved the H1/2026 interim dividend payment of 3.5 Baht per share, totaling 4,200 MB, equivalent to 24% of profit for H1/2026, to continuously care for shareholders. The dividend is payable on August 21, 2026, with the XD-date on August 5, 2026, and the record date on August 6, 2026.
ติดตามช่องทางมิติหุ้นเพื่อรับข่าวสารตลาดทุนได้ตามลิงค์ด้านล่าง
Web : https://www.mitihoon.com/
Facebook : https://www.facebook.com/mitihoon
Youtube : https://www.youtube.com/@mitihoonofficial7770
Tiktok : www.tiktok.com/@mitihoon